The global smartphone industry is currently witnessing a significant period of volatility following the highly anticipated release of the Apple iPhone Duo. While the arrival of Apple’s first foray into the foldable category was expected to accelerate mass-market adoption, early reports from consumers and independent technical analysts indicate substantial hardware concerns. These reports, which include accounts of display failures and mechanical issues within the hinge assembly, have cast a shadow over Apple’s launch, simultaneously highlighting the competitive advantage held by established players like Samsung.
As Apple navigates this challenging product rollout, the market dynamics surrounding foldable devices are undergoing a rapid transformation. With Samsung’s Galaxy Z Fold 8 series having undergone years of iterative refinement, the contrast between the two tech giants’ approaches to complex form factors has become a central topic of discourse among analysts, supply chain experts, and consumers alike.
A Chronology of the Foldable Market Expansion
The journey toward foldable devices has been a long-term strategic priority for several manufacturers. Samsung initiated its serious push into the segment with the launch of the original Galaxy Fold in 2019. Despite an initial delay due to screen durability concerns—a crisis that forced Samsung to redesign the device’s protective layers—the company successfully pivoted to a more robust, iterative cycle.
By 2026, the industry had reached a state of maturity, with Samsung’s Galaxy Z Fold 8 and Z Flip 8 representing the eighth generation of their respective lines. During this period, the technology evolved from a high-risk novelty to a functional productivity tool. Apple’s entry, marked by the announcement of the iPhone Duo, was viewed by many as the "final validation" of the foldable category. However, the timeline of the iPhone Duo’s release has been marred by logistical setbacks, including supply chain bottlenecks and, more recently, reports of structural vulnerabilities.
Technical Analysis: The Hinge and Display Dilemma
The primary concerns surrounding the iPhone Duo center on its mechanical architecture. Teardown reports published in the wake of the device’s release suggest that the internal hinge mechanism may suffer from friction-related issues or debris intrusion. In several documented instances, the display has shown signs of fracturing along the fold line within hours of unboxing.
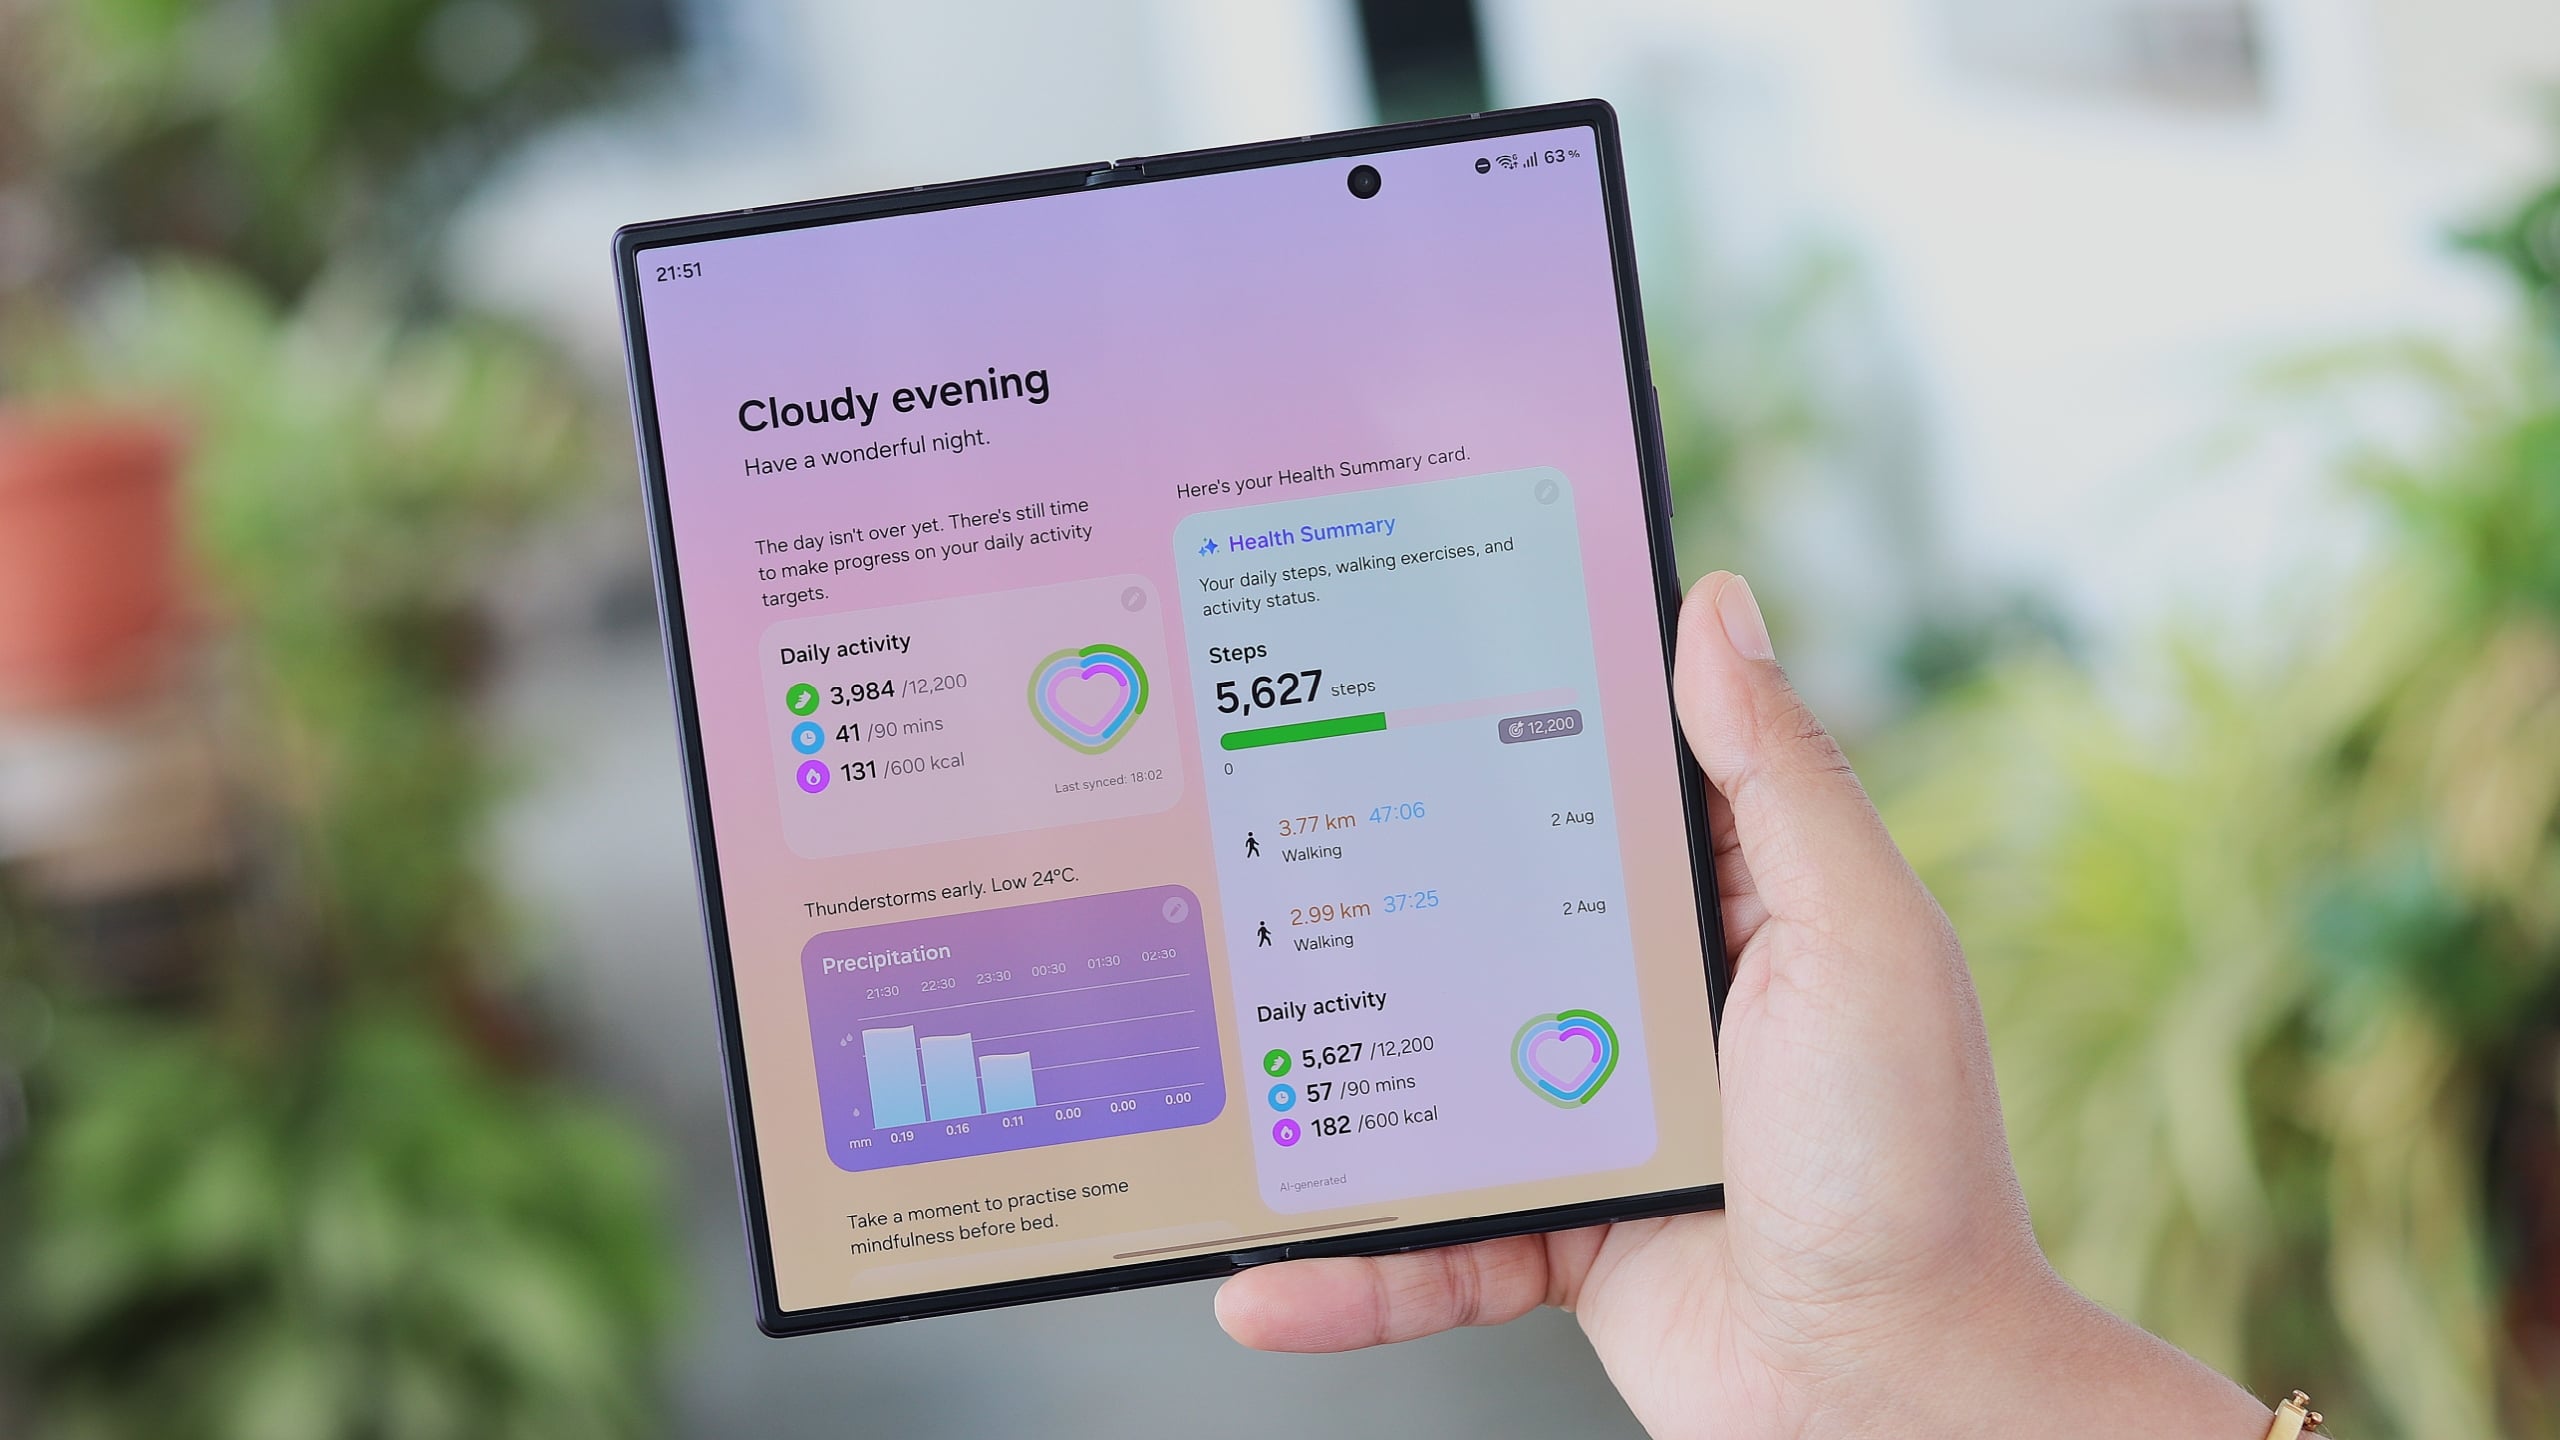
Engineers familiar with foldable display technology note that the tension applied to the flexible OLED panel is a critical variable. Samsung’s implementation utilizes a "teardrop" hinge design, which minimizes the crease and reduces the mechanical stress placed on the ultra-thin glass (UTG) layer. In contrast, the reported failures in the iPhone Duo suggest that its hinge might not be providing the necessary clearance or support for the display panel, leading to localized pressure points that manifest as physical damage.
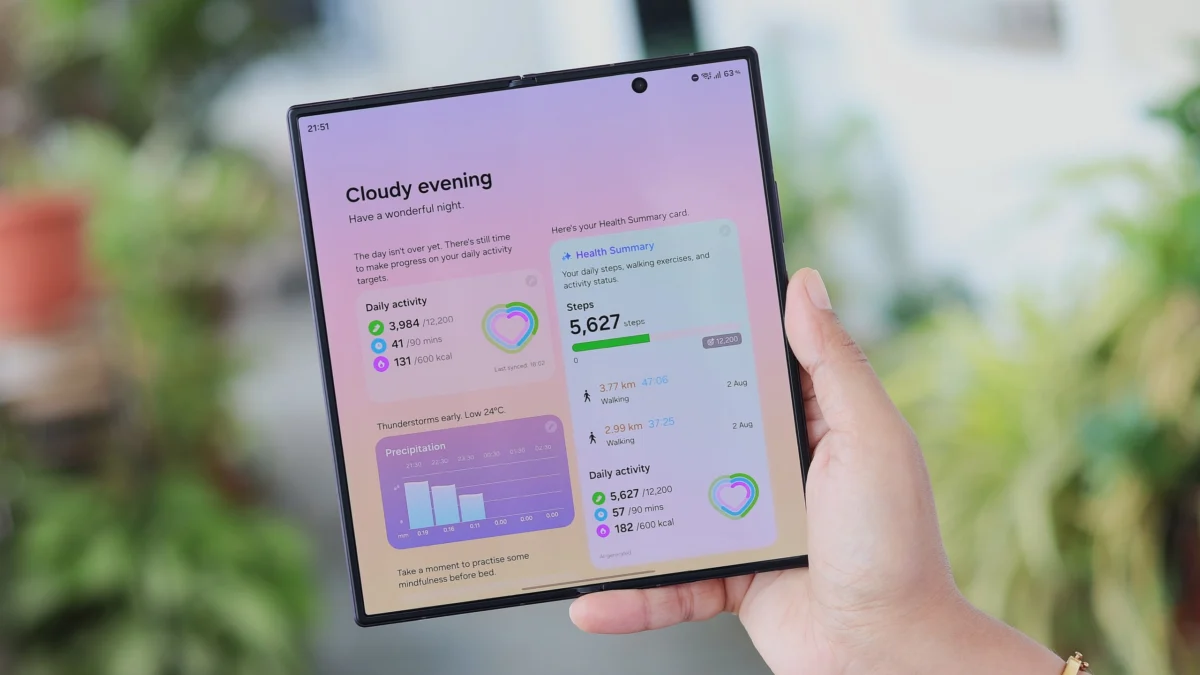
Comparative stress testing has shown that the Galaxy Z Fold 8 remains resilient under similar conditions. Samsung’s thinner, lighter profile for the Z Fold 8 is the result of eight years of metallurgical advancements and hinge testing, which has allowed the company to optimize the weight-to-durability ratio.
Economic and Market Implications
The broader implications of these developments are significant. Apple’s entry into the foldable space was expected to drive the market to new heights, potentially doubling the total addressable market for foldable devices by the end of 2026. However, if the quality control issues regarding the iPhone Duo are confirmed to be widespread, it could lead to a temporary loss of consumer confidence in the entire category.
Conversely, this scenario presents a rare window for Samsung to solidify its leadership position. Historically, Apple’s brand loyalty often shielded it from initial product failures, but in the premium foldable segment, consumers are less likely to tolerate technical compromises given the high price points associated with these devices. Data from recent market analysis firms suggest that consumer retention rates for foldable phones are currently higher among Samsung users than in other emerging foldable ecosystems, primarily due to the established nature of the Galaxy service and support network.
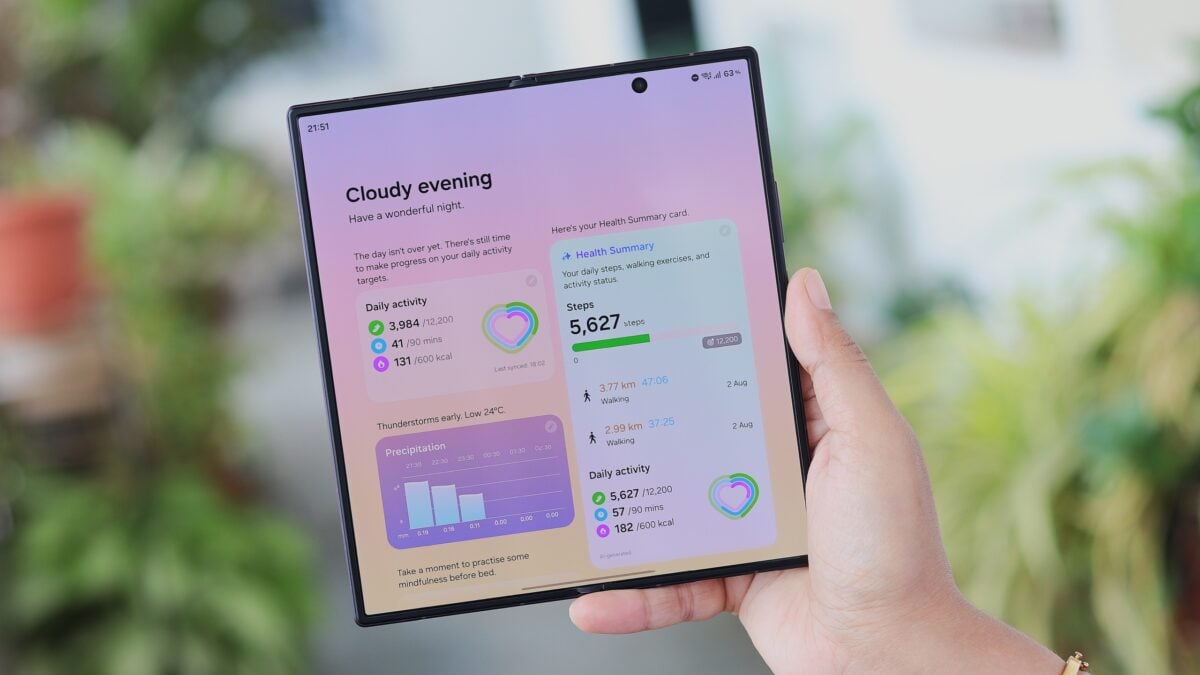
Strategic Recommendations for Market Consolidation
To capitalize on this shift, industry observers suggest that manufacturers must pivot from purely defensive marketing to a more proactive strategy centered on reliability and ecosystem maturity.
- Targeted Lifecycle Programs: Establishing trade-in programs that specifically cater to users of early-generation foldable devices—regardless of the brand—could effectively capture a segment of the market currently experiencing buyer’s remorse. By lowering the barrier to entry for the Galaxy Z series, Samsung could convert "early adopters" of rival technology into long-term loyalists.
- Transparency in Manufacturing: As consumer scrutiny regarding durability increases, companies that provide deep-dive insights into their manufacturing processes, material science, and rigorous testing standards will likely build more credibility. Samsung’s narrative of "refined iteration" stands as a powerful marketing tool in an environment where "first-generation" products are currently under fire.
- Software Integration and Continuity: Beyond hardware, the long-term success of a foldable device relies on software optimization. Samsung’s One UI, which has been tailored for the dual-display environment for years, offers a level of multitasking efficiency that is still in its infancy on competing platforms. Emphasizing this maturity will be essential as the market moves beyond the "wow factor" and into practical, daily utility.
The Outlook for 2026 and Beyond
The year 2026 is poised to be a defining moment for the mobile industry. The "foldable wars" are no longer about whether the technology is viable, but rather about which manufacturer can deliver a seamless, durable, and intuitive experience.
While Apple’s entry has undeniably brought unprecedented attention to the category, the technical challenges it currently faces underscore the difficulty of mastering flexible display engineering. Samsung’s position as the incumbent leader provides it with a distinct advantage, but this advantage is not guaranteed. It requires a concerted effort to communicate the benefits of its matured design language while simultaneously lowering the friction for users looking to switch from less stable alternatives.
As the industry moves forward, the focus will likely shift toward further reducing the weight of these devices while increasing the battery density—two areas where Samsung has made consistent, if incremental, gains. The current climate serves as a reminder that in the premium hardware sector, reliability is the most valuable feature. As Samsung continues to refine the Galaxy Z Fold 8 and prepare for future iterations, its ability to maintain its engineering edge will be the decisive factor in whether it retains its status as the premier foldable manufacturer.
Ultimately, the market will reward the company that can best balance the promise of futuristic form factors with the pragmatic requirement of day-to-day dependability. For now, the spotlight remains firmly on the durability of these devices, and the manufacturers that can navigate these concerns with transparency and technical excellence will likely dictate the direction of the mobile market for years to come.
